Key Takeaways
- Co-op buyers purchase shares in a corporation and receive a proprietary lease.
- Condo buyers own a deeded unit and share responsibility for common areas.
- Townhouse owners typically control the whole building and take on its repair obligations.
- Purchase price is only one part of the decision. Monthly charges, taxes, insurance, rules, and future flexibility matter just as much.
- The best fit depends on finances, lifestyle, renovation plans, and the amount of responsibility a buyer wants to manage.
In New York City, New York, two homes on nearby blocks can produce very different ownership experiences. A prewar co-op near Central Park, a full-service condo in Chelsea, and a West Village townhouse may all offer desirable Manhattan living, but they come with different rights, costs, approval processes, and maintenance responsibilities.
For buyers comparing those choices, New York NY real estate expert Eileen Robert and the team at Eileen Robert and Paolo Valois-Lopes provide Manhattan-focused property and neighborhood guidance through a website that features residential listings and local market insight. Their work across areas, including the West Village, Greenwich Village, Chelsea, SoHo/NoHo, and the Upper East Side, gives buyers a useful perspective when weighing luxury condos, co-ops, and townhouses beyond the asking price alone.
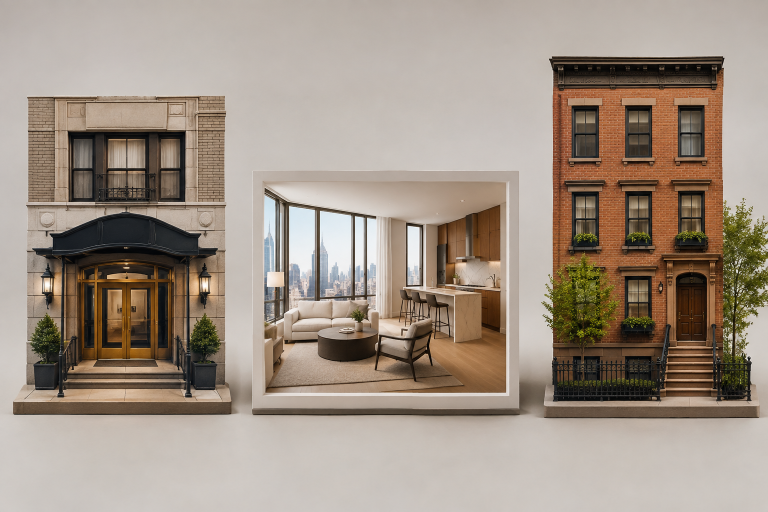
Co-Ops, Condos, and Townhouses at a Glance
- Co-op: You buy shares in the corporation that owns the building, plus the right to occupy a specific apartment through a proprietary lease. Monthly maintenance commonly includes a share of building operating costs and real estate taxes.
- Condo: You receive a deed to a particular unit and an ownership interest in shared areas. Monthly expenses generally include common charges and separately listed property taxes.
- Townhouse: You generally own the building and land directly. There is often no building-wide maintenance fee, but the owner is responsible for the roof, facade, systems, insurance, utilities, and repairs.
Do not assume that a home described as “townhouse-style” has traditional townhouse ownership. Confirm the deed, governing documents, and legal property structure before making an offer.
How Co-Op Ownership Works
A co-op corporation owns the building, and buyers purchase shares allocated to an apartment rather than taking title to a unit. This structure can make the building board a significant part of the purchase process. Board packages may request financial statements, tax returns, employment information, reference letters, and details about the buyer’s intended use of the home.
Buyers should read the house rules closely. Subletting, pied-à-terre use, pets, gifts, guarantors, and renovations may be subject to building-specific restrictions. Before signing, it is prudent to review financial statements, recent meeting minutes, planned capital work, reserve information, and any assessment history. The New York Attorney General advises prospective co-op and condo purchasers to read the offering plan and consult an attorney before signing a purchase agreement.
How Condo Ownership Works
A condo is deeded real property, which can offer a more straightforward ownership structure for buyers who value flexibility. Condo boards may still review purchasers and retain rights described in the building documents, but many condos have fewer occupancy and leasing restrictions than co-ops.
That flexibility can carry a higher entry cost. Compare common charges, real estate taxes, insurance requirements, current assessments, and the building’s policies for rentals and renovations. In a new development, the offering plan is especially important because it describes the sponsor’s obligations, unit specifications, common elements, and amenities.
How Townhouse Ownership Works
Townhouses can appeal to buyers who want privacy, multiple floors, private outdoor space, and more direct control over improvements. In return, the owner handles work that a co-op or condo building might coordinate collectively, including facade maintenance, waterproofing, heating and cooling equipment, plumbing, electrical upgrades, and structural repairs.
Townhouse due diligence should include:
- Reviewing tax records and the building’s legal use.
- Checking permits, complaints, violations, and certificates of occupancy.
- Inspecting the roof, facade, cellar, drainage, and mechanical systems.
- Determining whether landmark rules may affect exterior work.
- Setting aside a realistic reserve for repairs that may arise after closing.
Buyers can use the city’s building history tools to review permits, violations, complaints, and occupancy records for a New York City address. That research can be particularly valuable for older Manhattan townhouses with a long renovation history.
Compare the Full Monthly Cost, Not Just the Listing Price
A lower purchase price does not automatically mean a lower cost of ownership. Build a monthly budget that includes mortgage principal and interest, maintenance or common charges, property taxes, insurance, utilities, assessments, and a repair reserve.
For example, a co-op may have a lower asking price than a nearby condo but higher monthly maintenance. A townhouse may have no common charges, yet a roof replacement or boiler issue can create a substantial direct expense. Compare each option using the same assumptions for down payment, financing, monthly carrying costs, and available cash after closing.
Board Approval and Purchase Timing
Co-op transactions often require extra preparation because board review follows contract signing. Buyers can reduce avoidable delays by obtaining pre-approval, gathering financial documents early, understanding the building’s policies before making an offer, and avoiding major credit or employment changes while the application is under review.
Condo and townhouse timelines can also vary based on financing, inspections, title work, attorney review, and document availability. Leave room in the purchase plan for questions that emerge during due diligence.
Resale, Renting, and Lifestyle Fit
Think beyond the first year in the home. A condo may suit a frequent traveler or buyer who wants potential rental flexibility, subject to building rules. A co-op can be an excellent primary residence for someone comfortable with a more structured community. A townhouse may fit a growing household that values space and autonomy, provided the owner is prepared for hands-on property stewardship.
Questions to Ask Before Making an Offer
- What exactly am I buying: shares, a deeded unit, or an entire building?
- What are the total monthly carrying costs and known assessments?
- What restrictions apply to rentals, renovations, pets, or pied-à-terre use?
- How much liquidity or cash reserve does the building expect after closing?
- What do building records, inspection results, and financial documents reveal?
- Does this ownership structure support my likely plans for the next five to ten years?
Conclusion: Choose the Structure That Supports the Whole Plan
The right New York City home is not necessarily the newest, largest, or least expensive option. It is the property whose ownership structure matches the buyer’s budget, schedule, lifestyle, and tolerance for rules or maintenance. By comparing co-op, condo, and townhouse ownership in full, buyers can make a decision that works well long after closing day.